
The first step in finding small business funding for women is to calculate what the business needs the money for. Buying a machine for confirmed orders is different from borrowing to test whether an idea has customers. The amount, timing and expected return should guide the funding choice.
Access to finance can help a viable business grow. Borrowing before demand is clear can put pressure on both the business and household budget.
Table of Contents
Small Business Funding for Women Guide: Calculate the Gap
List the purchase or activity you want to fund, its full cost and when payment is due. Subtract money the business can reasonably contribute. Then estimate how the investment may generate enough cash to cover its costs.
Include working capital. A business might need money for materials and delivery weeks before customers pay. Keep a reserve for delays, repairs or returns rather than using every rupee for the main purchase.
Best Small Business Funding for Women: Compare the Options
| Funding source | Possible use | Main trade-off |
| Savings or retained earnings | Testing or gradual expansion | Limits what you can spend; personal savings may be at risk |
| Customer deposits or pre-orders | Materials for confirmed orders | You must deliver on the promised terms |
| Business loan | Equipment or working capital | Repayment and total borrowing cost |
| Eligible grant or programme | A specific permitted project | Eligibility, application rules and uncertain selection |
| Equity investment | A model designed for substantial growth | Giving up a share of ownership and decision-making |
The best funding source depends on the business and its cash flow. A grant is not guaranteed, and a loan remains repayable even if sales disappoint.
Small Business Funding for Women for Beginners: An Application Workflow
- Define the purpose. State exactly what the funds will buy.
- Calculate the full amount. Include setup, delivery and a realistic reserve.
- Prepare records. Organise sales, expenses, expected orders and available business documents.
- Compare written terms. Review interest, fees, repayment dates, security requirements and consequences of late payment.
- Test an adverse case. Could the business manage repayments if sales arrive later than expected?
- Apply through verified channels. Check the lender or programme’s official information before sharing documents.
Do not borrow the maximum offered merely because it is available. Borrowing should match a clear use and a plausible repayment plan.
Small Business Funding for Women Examples
A tailor with regular paid orders might consider funding a second machine after calculating whether additional work would cover repayments. A seller who receives confirmed custom orders may ask for a reasonable deposit to buy materials, provided delivery and refund terms are clear.
A founder developing a new product may investigate eligible startup programmes, but should first establish the project’s costs and check current criteria. Startup India’s official portal provides information on recognition and links to funding initiatives; recognition or application does not guarantee funding.
Small Business Funding for Women Cost and Expectations
The cost of a loan is more than its headline interest rate. Ask for the full repayment schedule and any processing, insurance or other charges. For investment, consider ownership and control alongside cash received. A customer deposit creates a delivery obligation.
Terms and scheme eligibility change. Compare current documents from the actual lender or programme rather than relying on a social media post. If you register an eligible MSME, the Government of India’s official Udyam portal says its registration process is free. Registration itself is not a promise of finance.
Small Business Funding for Women Tips
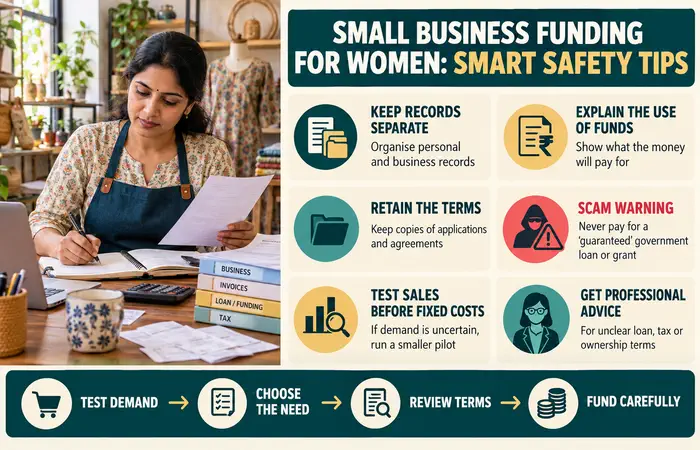
Keep personal and business records clear. Explain honestly how funds will be used and retain copies of application terms. Be cautious of anyone demanding a fee to “guarantee” a government-backed loan or grant.
A common mistake is funding fixed costs before testing sales. If demand remains uncertain, consider a smaller pilot that can be paid for from savings or early customer revenue. Seek professional advice where loan terms, tax treatment or ownership arrangements are unclear.
FAQs
Is there one best small business funding option for women?
No. Compare options against the amount needed, the purpose, cash flow and obligations attached.
Does Udyam registration guarantee a business loan?
No. The official Udyam portal covers registration; lenders assess finance applications separately.
Should I apply for funding before my first sale?
Some models require early funding, but a small paid test can provide useful evidence before taking on obligations.
Conclusion
Small business funding for women should support a specific, costed plan. Start with the funding gap, compare the full obligations of each option and choose an amount the business can realistically use and manage.